Term vs. Whole Life Insurance: Which One Actually Fits Your Budget?
Martha
a financial advisor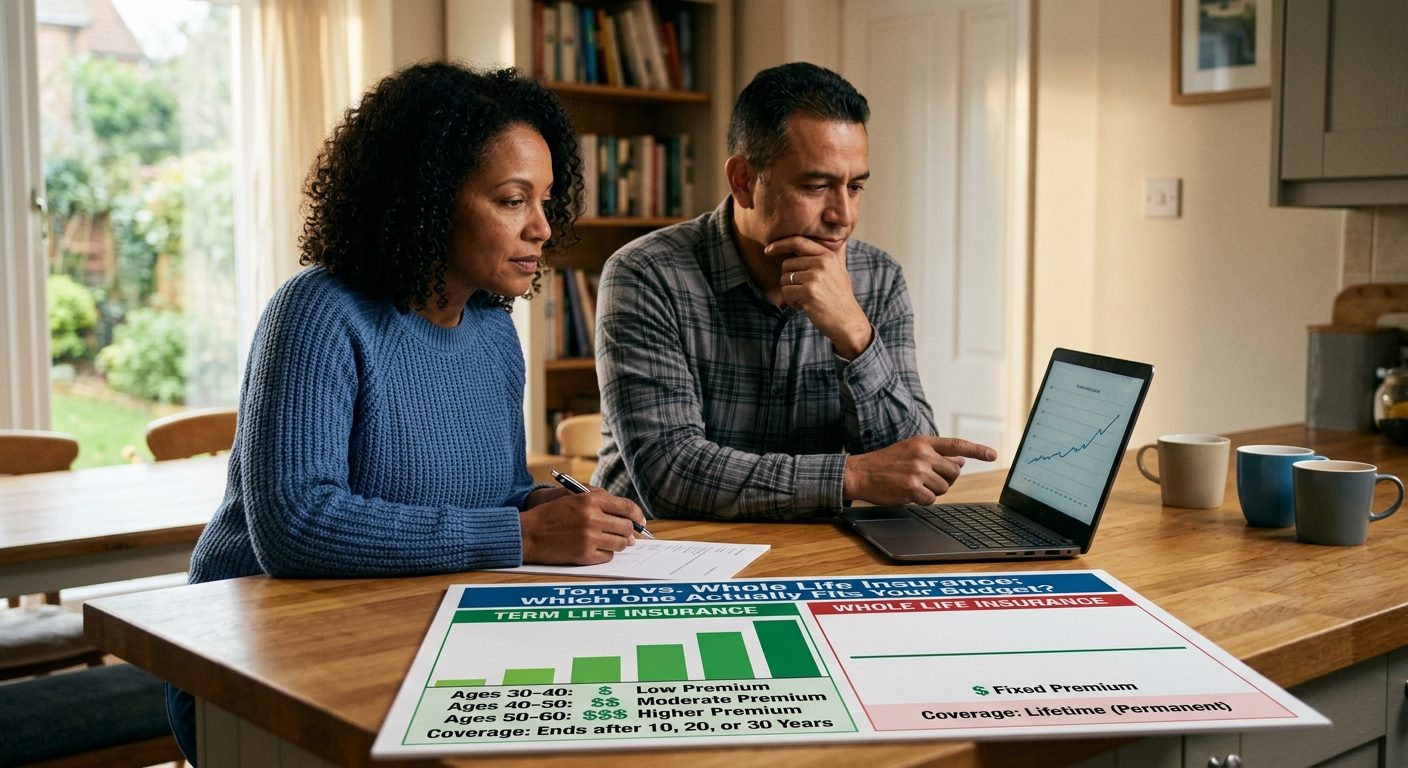
The real question behind term vs whole life insurance
Term vs whole life insurance isn't really a fight between two products. It's a bet about which version of your future you're willing to pay for right now. One protects your family for a fixed number of years and then walks away. The other protects them forever, and charges accordingly.
Most articles on this compare premiums, mention cash value once, and call it done. That's not the same as telling you which one actually fits your budget, which is the question that brought you here.
Before you compare anything, decide what you're judging on
Two people can look at the same $500,000 policy and walk away with opposite conclusions, because they're weighing different things without realizing it. So here's what actually matters when you set term vs whole life insurance side by side, before premiums, pitches, or guarantees enter the picture:
The monthly premium measured against take-home pay, not the sticker price on a quote page.
What happens to your coverage after the term ends, or if premiums ever get skipped.
Whether you need protection for a fixed stretch of years or for the rest of your life.
What the money does if you're one of the many people who never files a claim.
Everything below gets judged against those four things. Nothing else.
What term life insurance actually costs
For a 30-year-old non-smoking woman, a 20-year term policy worth $500,000 runs about $22.98 a month, according to Policygenius. That's the number every whole life pitch has to compete against, and it rarely does.
Term life insurance premiums are driven almost entirely by age, health, and how long you want the coverage to last. A 20-year term bought at 30 is cheap because the insurer is betting, correctly most of the time, that you'll outlive the policy. Push the term length out to 30 years or buy in your late 40s and the same math shifts noticeably, since life insurance cost by age climbs faster than most people expect once you're past 40.
Why it's structured this way
There's no cash value sitting inside a term policy. Every dollar of premium goes toward the odds calculation for that specific window of years. When the window closes, so does the coverage, unless you renew at a sharply higher rate or convert it to a permanent policy under whatever conversion rider your carrier included.
What whole life insurance actually costs
The same $500,000 policy, sold as whole life to that same 30-year-old, runs about $408 a month, per Policygenius — close to eighteen times the term price for an identical death benefit.
The reason isn't just profit margin. Insurers pool whole life premiums into a participating fund that gets reinvested to build cash value and generate non-guaranteed bonuses, according to Great Eastern Life. That's where permanent life insurance benefits like a growing cash balance actually come from, and it's also where a meaningful slice of your premium goes instead of straight into protection.
Buying earlier narrows the gap, but it never closes it. A standard non-smoking man buying a whole life policy with a RM100,000 sum assured pays roughly RM1,362 a year at age 20, RM1,705 at 30, and RM2,257 at 40, according to AIA Malaysia. Wait a decade and the same coverage costs meaningfully more, whichever type of policy you're comparing it against.
What you're paying for, ultimately, is duration. Whole life insurance policies guarantee coverage for life, typically up to age 95 or 102 as long as required premiums keep getting paid, per Forbes. Term life insurance premiums buy you a window instead — 10, 20, maybe 30 years — and then the coverage simply stops.
What term vs whole life insurance actually looks like side by side
Numbers land better next to each other than scattered across paragraphs, so here's the shape of the decision in one place.
Feature | Term Life | Whole Life |
|---|---|---|
Monthly cost, $500k, age 30 non-smoking female | ~$22.98 | ~$408 |
Coverage length | 10, 20, or 30 years | Lifetime, typically to age 95–102 |
Cash value | None | Builds slowly, can be borrowed against later |
Premium after policy ends or lapses | Coverage stops unless renewed or converted | Guaranteed for life if premiums are maintained |
Best suited to | Income replacement during working years | Estate planning, lifelong dependents, final expenses |
Term vs whole life cost: the short answer
When people compare term vs whole life cost, this is the gap they usually mean. For the same $500,000 of coverage, term life insurance costs a small fraction of what whole life charges. Using the Policygenius figures quoted in this article for a healthy 30-year-old non-smoker, a 20-year term policy runs about $22.98 a month, while whole life runs about $408 a month — roughly eighteen times more for an identical death benefit. That is a difference of about $385 a month, or about $4,620 a year.
| Policy ($500,000 cover, age 30) | Monthly premium | Per year | Over 20 years |
|---|---|---|---|
| 20-year term life | About $22.98 | About $276 | About $5,515 |
| Whole life | About $408 | About $4,896 | About $97,920 |
The table uses the article's quoted example only, and whole life premiums normally continue for life rather than stopping at 20 years — it is there to show the size of the gap, not to quote your price. Why is the gap so wide? Term is pure protection for a set number of years, with no cash value inside it. Whole life bundles lifelong coverage with a cash-value component and higher insurer costs, and you pay for all three in every premium. Both types get more expensive the older and less healthy you are when you buy, and term premiums can jump sharply if you renew after the term ends, while whole life premiums typically stay level for life. So the honest answer to the cost question is: term is far cheaper per dollar of protection, and whole life costs far more because it is built to last forever and to build cash value along the way. Get quotes for your own age, health, and coverage amount before deciding — prices vary a lot from person to person.
What "buy term and invest the difference" actually does to your money
This is the piece most term vs whole life insurance comparisons skip entirely, and it's the one with the biggest financial consequence.
Take that same 30-year-old: $22.98 a month for term versus $408 for whole life is a gap of about $385 a month, or roughly $4,620 a year. Put that difference into a broad-market index fund instead of a whole life premium, and assume a conservative 7% average annual return over 20 years. Run the compounding on that and you land somewhere around $200,000 by year twenty, before taxes and fees are accounted for.
That figure isn't a guarantee, it's arithmetic on the numbers above — but it's the calculation almost nobody shows you next to a whole life sales quote.
Real returns won't be smooth like that. Some years will be down 15%, some up 25%, and the sequence matters more than the average. But the underlying point holds even with worse timing: the gap between term life insurance premiums and whole life premiums is large enough, over decades, that most people are better off investing it than paying it to an insurer for permanent life insurance benefits they may never need.
The surrender problem nobody puts in the brochure
Whole life insurance cash value doesn't show up the way people expect. In the early years, a large share of each premium pays for the insurer's costs and the agent's commission before anything is credited to your cash balance. Surrender the polic
Disclaimer: This article is for general education only and is not financial, legal, or tax advice. Insurance prices and policy terms vary by insurer, age, and health, so consider seeking qualified professional advice for decisions specific to your situation.
Related guides
- How to Budget With Irregular Income: A Calm Plan for Paychecks That Change
Learn how to budget with irregular income: base your plan on your lowest month, build a buffer in good months, and pay bills in priority order so a slow month stays calm.
- How to Do a No-Spend Week in 2026: A Simple 7-Day Reset That Actually Feels Doable
How to do a no-spend week: set your own rules, stock the kitchen, plan free activities, and use seven days to notice where your money usually slips away.
- How to Save for Moving Costs in 2026: A Simple Plan That Actually Works
How to save for moving costs and a security deposit: list every cost, get real quotes, add a buffer, and save a fixed amount each payday so the big bills do not land all at once.