Debt Snowball vs. Debt Avalanche: Which Payoff Method Actually Saves You More
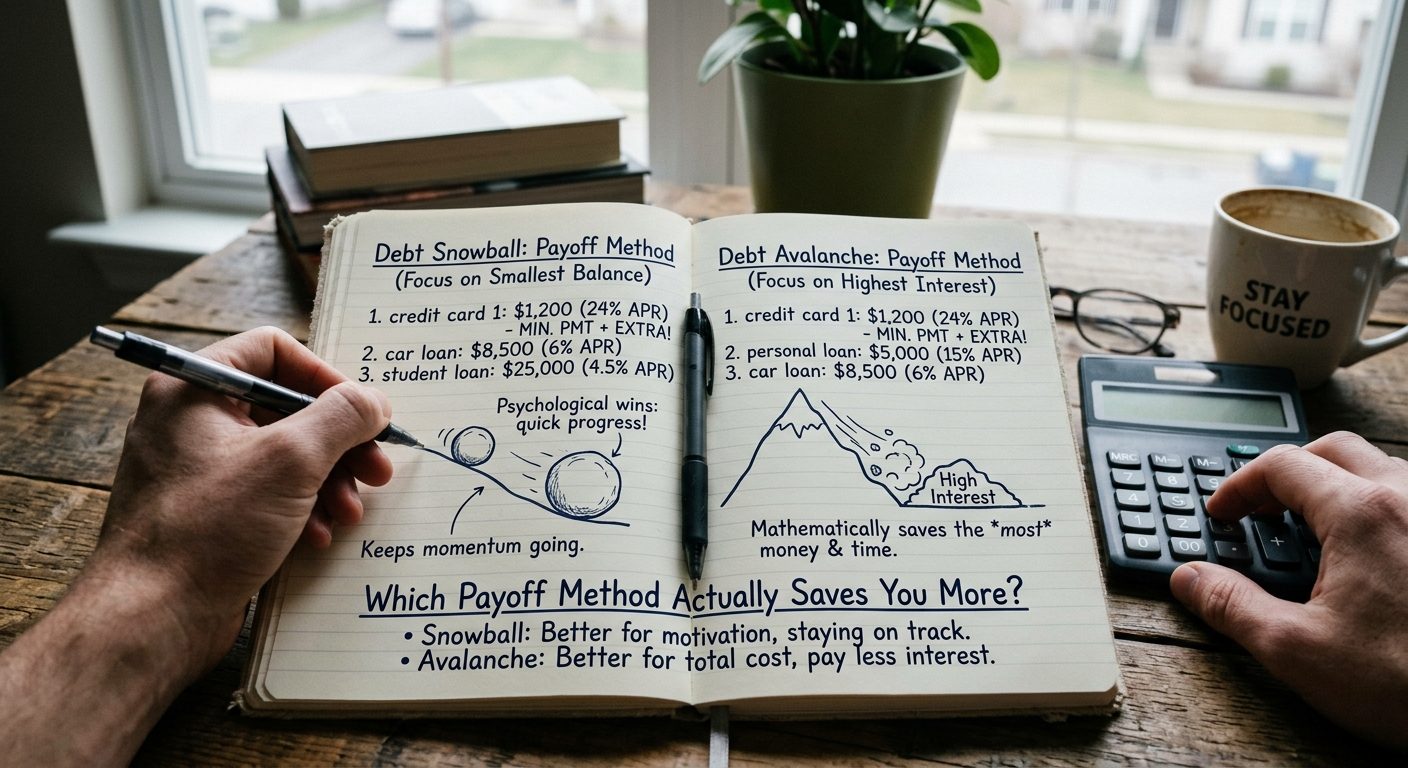
Debt Snowball vs Avalanche: Which Method Actually Gets You Out of Debt Faster?
If you're carrying multiple debts, credit cards, a car loan, maybe a personal loan, you've likely come across two competing strategies for paying them off: the snowball method and the avalanche method. The debt snowball vs avalanche debate has been going on for years, and both sides have passionate advocates. This guide breaks down what the actual research shows, not just opinion, so you can choose the approach that fits your real financial situation.
What Each Method Actually Does
The debt snowball method has you list your debts from smallest balance to largest, regardless of interest rate. You pay minimums on everything except the smallest debt, which gets every extra dollar you can spare. Once that's paid off, you roll its payment into the next-smallest balance, and so on, building momentum as you go, much like a snowball gaining size as it rolls downhill.
The debt avalanche method works differently. Instead of ordering debts by balance, you order them by interest rate, highest to lowest. All extra payments go toward the debt charging you the most interest first, regardless of how large or small that balance is. Mathematically, this should always save you more money over time, since you eliminate your most expensive debt sooner.
Debt snowball vs avalanche: the short answer
If you are comparing debt snowball vs avalanche and just want the answer first: the avalanche usually costs less, and the snowball usually feels easier. With the avalanche, you attack the debt with the highest interest rate first, so less of your money leaks away as interest. With the snowball, you clear the smallest balance first, so you get a finished debt sooner. The research section below puts it in perspective: in a LendingTree modelling exercise quoted in this article, the two methods produced identical results in two of four household scenarios, and they only pulled apart when one debt carried a much higher rate than the rest — in that scenario, the avalanche saved roughly $1,292 and finished about a month sooner.
| Method | Pay off first | Why people pick it | The trade-off |
|---|---|---|---|
| Debt snowball | Smallest balance, whatever its rate | Quick wins that keep motivation high | Can cost more in interest overall |
| Debt avalanche | Highest interest rate, whatever its balance | Lowest total cost in pure maths | The first cleared debt can take longer |
So, snowball vs avalanche debt payoff — which one should you actually choose? If your debts carry very different interest rates, especially an expensive credit card next to cheaper loans, the avalanche puts real money back in your pocket. If you have started payoff plans before and quit, the snowball's early wins may be worth a modest amount of extra interest, because the plan only works if you are still following it in month six. Both methods run on the same rules: pay the minimum on every debt, throw every spare dollar at the one target debt, and when it is gone, roll that whole payment into the next one.
One related search term is worth clearing up: 'avalanche savings account.' There is no special account with that name — the savings in the avalanche method are simply the interest you never pay. In the high-rate LendingTree scenario above, that saving came to roughly $1,292 compared with the snowball route. Money saved that way still needs a home, and a sensible one is an ordinary savings account kept separate from your everyday spending — ideally the start of a small emergency fund. The habit works in two steps: let the avalanche method create the savings by clearing your most expensive debts first, then move what you save into that account, so the next surprise bill does not push you straight back into debt.
Want to see both methods with your own numbers? Our free debt payoff calculator lets you enter your balances, interest rates and minimum payments and compares the snowball and avalanche side by side — your debt-free date, total interest and payoff order for each.
What the Research Actually Shows
This is where the comparison gets genuinely interesting, because the data doesn't always match the popular narrative.
A widely cited academic analysis using Federal Reserve Survey of Consumer Finance data found that while the avalanche method is mathematically more efficient in most cases, the snowball method performs as a remarkably close competitor, largely because of the psychological and habit-forming benefits it offers borrowers.
A separate study by LendingTree modeled four realistic household debt scenarios and found something worth paying attention to: in two of the four cases, both methods produced identical payment sequences and identical costs. The two methods only diverged meaningfully when one debt carried a significantly higher interest rate than the others, in one scenario, the avalanche approach saved roughly $1,292 and shaved a month off the payoff timeline.
Separately, research referenced by financial planners has pointed to a key behavioral insight: completion rates depend less on total debt amount and more on how many individual accounts a person believes they can realistically close. This helps explain why the snowball method, despite costing more in interest on paper, so often outperforms avalanche in real-world completion rates.
When the Numbers Really Diverge
The size of the gap between these two outcomes depends heavily on how spread out your interest rates are.
If your debts all carry similar rates (say, within a few percentage points of each other), the method you choose barely matters financially. You might save $100–$300 total by choosing avalanche.
If you're carrying a mix of low-rate debt (like a car loan around 6%) alongside high-rate credit cards (20%+), the avalanche method's advantage becomes much more significant, often saving $500 to over $2,000 in total interest, depending on your balances and timeline.
One detail that surprises many people: increasing your monthly extra payment amount has roughly twice the financial impact of switching between the two methods. In other words, finding an extra $100 a month to put toward debt matters more than which method you pick.
Which Method Should You Choose?
There's no universally "correct" answer here, and any financial guide claiming otherwise is oversimplifying. The right choice depends on your personality and your specific debt profile.
Choose the snowball method if:
You've tried to pay off debt before and lost motivation partway through
You have several smaller debts that could realistically be closed within a few months
You need visible proof of progress to stay disciplined
Choose the avalanche method if:
You're comfortable delaying gratification for a larger financial payoff
At least one of your debts carries a significantly higher interest rate than the rest
You're the type who stays motivated by tracking numbers rather than milestones
Consider a hybrid approach if:
You want to start with one or two quick wins for motivation, then switch to targeting your highest-interest debt once you've built momentum. Many financial counselors informally recommend this blended approach for borrowers who aren't sure which camp they fall into.
A Practical First Step
Regardless of which side of the debt snowball vs avalanche debate you land on, the research is consistent on one point: having any deliberate, organized payoff strategy dramatically outperforms making scattered extra payments without a plan. Before choosing a method, list every debt you owe with its balance, interest rate, and minimum payment. That single step makes the decision far more concrete than comparing the two methods in the abstract.
Disclaimer: This article is for general education only and is not financial, legal, or tax advice. The right payoff method depends on your balances, interest rates, and habits, so consider seeking qualified professional advice for decisions specific to your situation.
Related guides
- How to Save $1,000 in 3 Months (A Week-by-Week Plan That Fits Real Paychecks)
Saving $1,000 in three months is about $77 a week, thirteen times. A week-by-week plan that fits real paychecks: automate it on payday, find the weekly amount in your current spending, and track it somewhere visible.
- Sinking Fund Categories: The Complete List, Prioritised by Your Situation
Long sinking fund category lists do not tell you where to start. Prioritised starter sets by situation - renter or homeowner, car or no car, kids or no kids - so you can pick your first 3 to 5 funds.
- What Bills to Pay First When Money Is Tight (A Calm Priority Order)
Can't cover everything this month? A calm priority order for tight months: housing, utilities, food and transport before unsecured debt — plus who to call before you miss a payment.
Put the numbers side by side with the free debt payoff calculator, which compares the snowball and avalanche methods using your own balances and APRs.
Browse more step-by-step guides in the Budgeting hub.