How to Save $1,000 in 3 Months — Without Waiting for a Raise
Luci Shut
# How to Save $1,000 in 3 Months — Without Waiting for a Raise
A thousand dollars is a strangely powerful amount of money. It is small enough to feel reachable and big enough to change how a bad week feels — a car repair, a broken appliance, a few lost shifts at work stop being emergencies and start being inconveniences.
Three months is about thirteen weeks. That is the whole trick: this goal is not "find $1,000." It is "find about $77, thirteen times." Here is a plan built around real paychecks.
The Short Answer
Yes — $1,000 in three months is about $77 a week, thirteen times, not one lump sum to find. Give the $1,000 a job first, automate the transfer on payday so it happens before spending starts, then find the weekly amount in your current spending and track it somewhere visible. The plan in this post works from your real paychecks, week by week.
First, Pick Your Version of the Maths
$1,000 in three months breaks down like this — pick the rhythm that matches how you are paid:
| How you're paid | Amount to set aside | Number of times |
|---|---|---|
| Weekly | About $77 a week | 13 weeks |
| Every two weeks | About $167 per paycheck | 6 paychecks |
| Monthly | About $334 a month | 3 months |
These are simple divisions of the goal, not promises about what your budget allows. If $77 a week is genuinely too much, stretch the timeline to four months (about $58 a week or $125 per biweekly paycheck) rather than abandoning the goal. A finished four-month plan beats a quit three-month one.
Step 1: Give the $1,000 a Job Before You Start
Saving "just in case" is easy to raid. Saving for a named job is harder to touch. For most people, this $1,000 is the start of an emergency fund — the buffer that keeps a surprise off a credit card. Our guide on how much to keep in an emergency fund, and where to keep it explains how this first $1,000 grows into three to six months of essentials over time.
Name the account or the pot with the job ("Emergency — do not touch") and keep it separate from everyday spending money. Separate is what makes it still be there in week nine.
Step 2: Automate It on Payday
Set an automatic transfer for the amount you chose, timed for payday or the day after. Willpower is unreliable in week six; automation is not. If your pay varies, set the transfer for the smallest amount that always works, and move extra across manually in good weeks.
Move the money before you start spending from the check. If the transfer happens after a week of everyday spending, there will rarely be enough left — not because you failed, but because that is how money behaves.
Step 3: Find the Weekly Amount in Your Current Spending
Most three-month plans are funded by a temporary squeeze in a few familiar places. You only need to find roughly $77 a week, and only for one season:
- Food: one planned grocery shop with a list instead of several top-up trips, and a "use it up" week for what is already in the cupboards and freezer.
- Subscriptions and memberships: pause or cancel for three months. A paused streaming or gym subscription is not forever — it is $10 to $50 a month toward the goal.
- Small daily spends: the coffee, snack, and delivery habits are where $10-a-day leaks live. You do not have to ban them; halving them often finds half the weekly target.
- One sale or extra shift: a single clear-out of unused items, or a couple of extra hours of work if available, can fund a week or two outright.
Treat the squeeze as a season with an end date, not a new personality. That mindset is what gets people to week thirteen.
Step 4: Track It Visibly
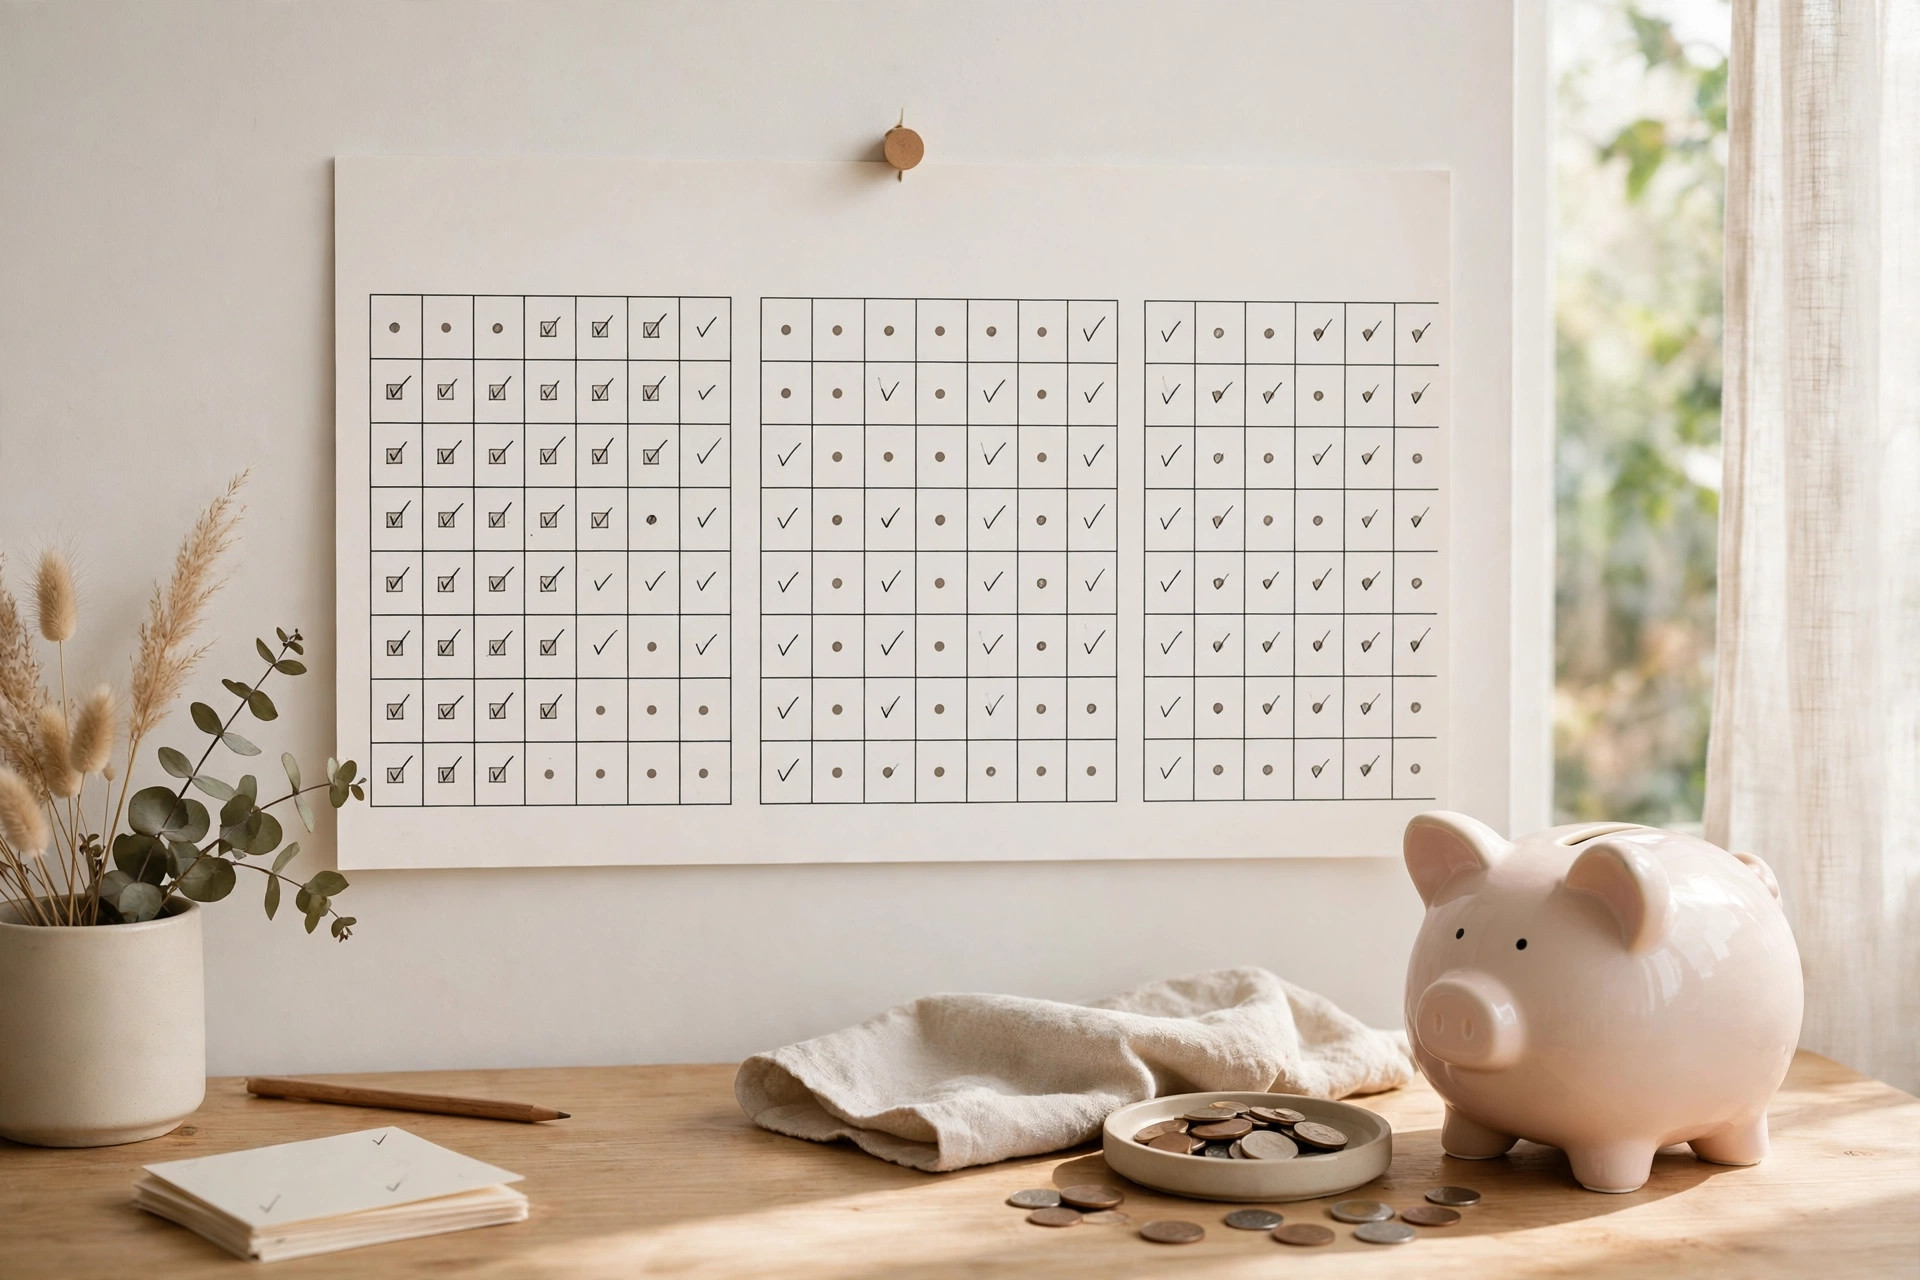
Draw or print a simple progress bar with thirteen boxes and fill one in each week. Put it on the fridge or as your phone wallpaper. It sounds childish and works anyway: visible progress makes the next transfer easier, and a skipped week shows up as one empty box to catch up — not a ruined plan.
If a week genuinely goes wrong, do not double next week's amount in a panic. Add a week at the end instead. The goal is $1,000 saved, not $1,000 saved on a perfect schedule.
A Worked Example (Illustrative Only)
This example is illustrative only, with round numbers — not real household data, and not a promise about your budget. Imagine Taylor, paid every two weeks, who sets aside $167 per paycheck:
| Paycheck | Set aside | Running total |
|---|---|---|
| 1 | $167 | $167 |
| 2 | $167 | $334 |
| 3 | $167 | $501 |
| 4 | $167 | $668 |
| 5 | $167 | $835 |
| 6 | $165 (rounding) | $1,000 |
Taylor funds it by pausing two subscriptions, one list-based grocery shop a week, and selling a few unused items in week two to cover a shortfall. Nothing exotic — just the same amount, moved on payday, six times in a row.
Frequently Asked Questions
Is $1,000 in 3 months realistic on a low income?
It depends on your margin, and it is fine if your honest answer is "not quite." The same plan stretched over four or five months — about $50 to $58 a week — gets you to the same $1,000. The deadline is flexible; the habit is the point.
Where should I keep the money while I save it?
In a separate savings account or labelled pot, away from everyday spending. For a three-month goal, easy access without fees matters more than earning interest — the amount of interest on $1,000 over three months is small either way.
What should I do when I reach $1,000?
Decide its job and leave it alone: for most people, it becomes the starter emergency fund. Then choose the next goal — growing the emergency fund further, or clearing a specific debt — and keep the same payday transfer running toward it.
What if I have to dip into it mid-plan?
That is what it is for. If a real emergency uses part of it, you have still proven the system works — restart the weekly amount and rebuild. Having $600 saved when the car breaks is infinitely better than having a perfect plan and $0.
Should I save $1,000 or pay off debt first?
A common sequence is: save this starter $1,000 first so surprises stop going on a card, then attack high-interest debt, then build the emergency fund further. If a debt is in collections or at a very high rate, your best order may differ.
Your $1,000-in-3-Months Checklist
- My rhythm picked: $77/week, $167/biweekly paycheck, or $334/month.
- A separate account or pot opened and named for the goal.
- Automatic transfer set for payday.
- Two or three temporary squeezes chosen to fund the amount.
- A visible tracker started (13 boxes, one per week).
- A "bad week" rule decided: add a week, don't quit.
- The goal's job named — for most people, a starter emergency fund.
The Bottom Line
The secret of how to save $1000 in 3 months is that there is no secret — it is $77 a week, moved on payday, into an account you do not touch, funded by a one-season squeeze on ordinary spending. Do that thirteen times and the number that once felt abstract is sitting in your account, ready for the day something breaks.
For more goal-based saving help, explore our Budgeting Guides.
---
Disclaimer: This article is for education only and is not financial advice. Everyone's finances are different, so consider your own situation, and speak to a qualified professional if you need personal financial guidance.
Related guides
- Sinking Fund Categories: The Complete List, Prioritised by Your Situation
Long sinking fund category lists do not tell you where to start. Prioritised starter sets by situation - renter or homeowner, car or no car, kids or no kids - so you can pick your first 3 to 5 funds.
- What Bills to Pay First When Money Is Tight (A Calm Priority Order)
Can't cover everything this month? A calm priority order for tight months: housing, utilities, food and transport before unsecured debt — plus who to call before you miss a payment.
- How to Budget for Annual Bills: A 12-Month Calendar That Ends Surprise Bills
Annual bills only feel like surprises because they are not on a calendar. A 12-month map of irregular expenses, with a per-paycheck amount for each bill.
Browse more step-by-step guides in the Budgeting hub.